
 394 お客様のコメント

F2の迅速なアップデート対応
F2試験に変更がございました場合は、現在の試験と一致するよう、瞬時に学習資料を更新することができます。弊社は、お客様に最高、最新のCIMA F2問題集を提供することに専念しています。なお、ご購入いただいた製品は365日間無料でアップデートされます。
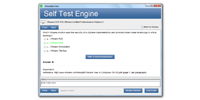
ダウンロード可能なインタラクティブF2テストエンジン
CIMA Managementの基礎準備資料問題集には、CIMA Management F2試験を受けるために必要なすべての材料が含まれています。詳細は、正確で論理的なものを作成するために業界の経験を常に使用しているCIMA Management によって研究と構成されています。
F2試験の品質と価値
JPNTestのCIMA Management F2模擬試験問題集は、認定された対象分野の専門家と公開された作成者のみを使用して、最高の技術精度標準に沿って作成されています。
あなたのF2試験合格を100%保証
JPNTestテスト問題集を初めて使用したときにCIMA Management F2試験(Advanced Financial Reporting)に合格されなかった場合は、購入料金を全額ご返金いたします。
JPNTestでCIMA F2問題集をチョイスする理由
JPNTestは、1週間で完璧に認定試験を準備することができる、忙しい受験者に最適な問題集を提供しております。 F2の問題集は、CIMAの専門家チームがベンダーの推奨する授業要綱を深く分析して作成されました。弊社のF2学習材料を一回のみ使用するだけで、CIMA認証試験に合格することができます。
F2はCIMAの重要な認証であり、あなたの専門スキルを試す認定でもあります。受験者は、試験を通じて自分の能力を証明したいと考えています。 JPNTest Advanced Financial Reporting は、CIMA Managementの212の問題と回答を収集して作成しました。Advanced Financial Reportingの知識ポイントをカバーし、候補者の能力を強化するように設計されています。 JPNTest F2受験問題集を使用すると、Advanced Financial Reportingに簡単に合格し、CIMA認定を取得して、CIMAとしてのキャリアをさらに歩むことができます。
CIMA F2 試験シラバストピック:
| セクション | 比重 | 目標 |
|---|---|---|
| 資本プロジェクトの資金調達 | 15% | |
| 統合報告およびサステナビリティ報告 | 10% | |
| グループ財務諸表 | 25% | |
| 財務報告基準 | 25% | |
| 財務諸表分析 | 25% |
CIMA Advanced Financial Reporting 認定 F2 試験問題:
Entity A entered into a 3 year operating lease on 1 April 20X3. The rentals are £5,000 a year payable in advance with an additional payment of $1,800 payable on 1 April 20X3.
The rental expense to be included in the statement of profit or loss for the year ended 31 December
20X3 will be:
- A. $4,200
- B. $5,000
- C. $6,800
- D. $5,600
正解:A 🗳️
The yield to maturity of a redeemable bond is calculated as the internal rate of return of the relevant cash flows associated with the bond.
Which TWO of the following are considered relevant cash flows in this calculation?
- A. The value of the conversion premium on conversion to equity shares.
- B. The nominal value of the bond now.
- C. The redemption value of the bond at the date of redemption.
- D. The annual interest payments net of tax relief.
- E. The market value of the bond now.
正解:C、E 🗳️
EFG is preparing its financial statements to 31 March 20X8. During the year ended 31 March 20X7, EFG purchased a piece of land for $1 million which is used as the staff car park. EFG has a policy of revaluing land, in accordance with International Accounting Standards, and at 31 March 20X8, accounted for a substantial increase in its value.
Revenue and operating profit has remained constant over the 2 years.
When comparing EFG's financial statements for the year ended 31 March 20X7 with those of 20X8, which THREE of the following would be expected?
- A. Decrease in net asset turnover.
- B. Decrease in return on capital employed.
- C. Increase in other comprehensive income.
- D. Increase in return on capital employed.
- E. Increase in profit before tax.
- F. Increase in net asset turnover.
正解:A、B、C 🗳️
Information extracted from JK's statement of financial position for the year ended 31 May 20X5 is as follows:
Calculate the gearing ratio (Debt/Equity measured as a percentage) at 31 May 20X5.
Give your answer to one decimal place.
? %
正解:
58.4, 58, 58.44, 59, 58.5, 58.0
JK is seeking to raise new finance through a rights issue of equity shares.
Which THREE of the following statements are correct?
- A. Shareholders must pay the full market price for shares offered in a rights issue.
- B. Entities have the opportunity to underwrite a rights issue.
- C. The administration costs associated with a rights issue are higher than those for an initial public offering.
- D. A rights issue will dilute an existing shareholder's control of the entity if they do not take up their rights.
- E. An alternative name for a rights issue is a scrip issue of shares.
- F. Shareholders' entitlement to rights may be sold on their behalf.
正解:B、D、F 🗳️
全 43 ページ中 1 ページ目を表示しています。
全 212 問中 1-5 問目を表示しています。


 0
 0
 0
 0
